The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Business life insurance ownership affects who controls the policy, who receives a claim payment and whether the cover supports key person, buy-sell or business debt protection planning. This guide explains common ownership and beneficiary structures for Australian businesses.
Choosing business life insurance is not only a question of premium, cover type or sum insured. For Australian business owners, co-founders, partners and directors, one of the most important structural questions is who should own the policy.
Policy ownership can affect who controls the cover, who pays premiums, who receives proceeds if a claim is paid and whether the arrangement works as intended for key person protection, buy-sell funding or business debt protection. The right structure depends on the purpose of the cover, the business structure, legal agreements, tax position and insurer requirements.
This article provides general information only. It is not legal, tax or personalised financial advice.
What policy ownership means
The policy owner is the person or entity that holds the contractual rights under the insurance policy. Depending on the policy and insurer, the owner may be able to:
- apply for and accept the policy;
- pay premiums or arrange for premiums to be paid;
- change certain policy details;
- nominate or change beneficiaries where the policy allows it;
- cancel the policy;
- receive notices from the insurer; and
- receive the claim proceeds, unless a valid beneficiary, assignment or other arrangement applies.
The life insured is the person whose death, terminal illness, disablement or trauma event may trigger a claim, depending on the type of cover selected. In a business context, the life insured might be a founder, director, shareholder, partner, guarantor, senior employee or another person who is financially important to the business.
The beneficiary is the person or entity intended to receive the policy proceeds. In some structures, the owner and beneficiary are the same. In others, proceeds may be directed through a nomination, assignment, trust arrangement or legal agreement. Availability and rules vary between insurers and policy types.
Why ownership matters for Australian businesses
Business life insurance ownership is a practical control issue. If the structure does not match the business purpose, a claim payment may be delayed, paid to an unintended party or create avoidable tax, estate or succession complications.
Ownership can influence:
- Control: who can maintain, alter or cancel the policy.
- Claim payment flow: whether proceeds go to the business, another owner, the insured person's estate, a lender or another party.
- Business continuity: whether funds are available to replace revenue, repay debt, fund a buyout or support working capital.
- Tax treatment: whether premiums and proceeds are treated as revenue or capital in nature may depend on purpose and structure.
- Estate planning: whether proceeds form part of a personal estate or are directed outside it.
- Legal consistency: whether the policy aligns with shareholder, partnership, trust, loan and buy-sell documents.
For these reasons, ownership should usually be considered before an application is submitted, not after cover is already in place.
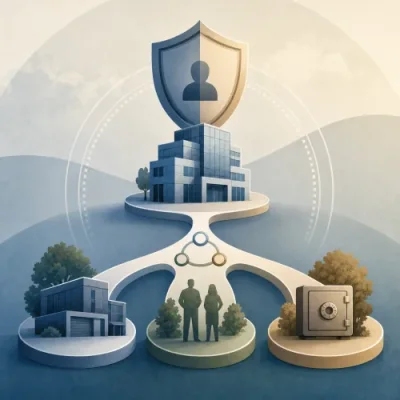
Common business life insurance ownership structures
There is no single ownership structure that suits every business. The following structures are commonly considered in business life insurance planning.
| Ownership structure | How it generally works | Common use cases | Key considerations |
|---|
| Business or entity-owned policy | The company, partnership or business entity owns the policy and is commonly the recipient of proceeds. | Key person cover, business debt protection and some entity-purchase buy-sell arrangements. | May align proceeds with business cash flow needs, but tax, shareholder and accounting issues should be reviewed. |
| Self-owned policy | The insured person owns the policy on their own life. | Personal protection, some buy-sell funding structures and cover linked to estate or family needs. | Provides personal control, but business agreements must clearly direct how proceeds are used if a business outcome is intended. |
| Cross-owned policy | One business owner owns a policy on another owner's life, and vice versa. | Some buy-sell or partnership succession arrangements. | Can become complex when there are several owners, ownership changes or unequal shareholdings. |
| Trust-owned policy | A trust owns the policy and proceeds are managed according to the trust deed and related agreements. | Some succession, estate planning or asset protection arrangements. | Requires careful legal and tax advice, and the trust deed must support the intended outcome. |
| Policy assigned or noted in favour of a lender | The policy may be owned by the business or individual, with rights assigned or noted in favour of a lender. | Business loan or personal guarantee protection. | The assignment should match loan requirements and may affect who receives proceeds first. |
Entity-owned life insurance for key person cover
For key person insurance, the business often owns the policy because the financial loss is expected to be suffered by the business. The life insured may be a founder, revenue generator, specialist employee, executive, director or other person whose death or disablement could materially disrupt operations.
When the business owns the policy, the claim proceeds can generally be directed to the business to help with costs such as:
- replacing lost revenue;
- recruiting or training a replacement;
- engaging temporary contractors or consultants;
- stabilising working capital;
- maintaining confidence with suppliers, lenders or customers; and
- funding a transition period after the loss of a key person.
The purpose of the cover should be documented. A policy intended to protect revenue may be treated differently from one intended to protect capital value, repay debt or fund an ownership transfer. Business owners should review the structure with appropriate advisers before relying on it.
Ownership for buy-sell insurance
Buy-sell insurance is used to help fund the transfer of an owner's interest if a trigger event occurs, such as death or total and permanent disablement, depending on the agreement and cover selected. In this setting, policy ownership must work together with the buy-sell agreement.
For example, if an agreement says the surviving owners must buy the departing owner's shares, the insurance proceeds need to be available to the party that has the purchase obligation. If the company is expected to buy back or redeem the interest, the policy structure may need to support that entity-purchase approach.
Common buy-sell insurance ownership models include:
- Cross-ownership: each owner holds insurance on the other owners. This may suit simple ownership groups but can be harder to administer as the number of owners grows.
- Self-ownership: each owner owns their own policy, with the buy-sell agreement setting out how proceeds are to be applied. This can be administratively simpler in some cases, but the agreement must be carefully drafted.
- Entity ownership: the company or business entity owns the policies and receives proceeds. This may align with an entity-purchase arrangement, but it raises tax, accounting, Corporations Act and shareholder considerations that need professional advice.
- Trust ownership: a trust may hold the policies for the benefit of relevant parties. This can be flexible but requires careful legal structuring.
The important point is consistency: the policy owner, beneficiary pathway and legal obligation to buy or sell should all point to the same intended outcome.
Ownership for business debt protection
Business debt protection cover is commonly considered where a business loan, commercial facility or personal guarantee depends heavily on one or more owners or directors. The aim is to provide funds that may help reduce or repay debt if the insured person dies or suffers another insured event.
Ownership may depend on who owes the debt and who is exposed if it is not repaid. Possible structures include:
- the business owning the policy if the business is the borrower;
- a guarantor owning cover personally if their personal assets are exposed;
- a company-owned policy with arrangements to apply proceeds towards business liabilities; or
- a policy assigned or noted in favour of a lender, where required and accepted.
Lenders may have their own requirements. However, a lender requirement does not automatically mean the policy is suitable, sufficient or correctly structured for all owners. Loan documents, guarantee terms and insurance policy documents should be reviewed together.
Who should be the beneficiary?
The beneficiary should usually be the person or entity that needs the money to achieve the insurance purpose. In practice, this may be the same as the policy owner, but not always.
For key person insurance, the business is often the intended recipient because the business needs the cash flow support. For buy-sell insurance, the intended recipient may be the surviving owners, the departing owner, the estate, a trust or the company, depending on how the buy-sell agreement is drafted. For debt protection, proceeds may be intended for the business, a guarantor, a lender or a combination of parties.
Before deciding on a beneficiary or claim payment pathway, consider:
- who will suffer the financial loss;
- who has the legal obligation to buy shares, repay debt or fund continuity costs;
- whether the policy allows the intended beneficiary structure;
- whether any nomination may lapse or be invalid in particular circumstances;
- whether proceeds could become part of an estate and be subject to estate disputes;
- whether the arrangement is consistent with company, trust, partnership and shareholder documents; and
- whether tax consequences have been reviewed.
Tax implications of ownership and purpose
Tax treatment is one of the main reasons policy ownership should not be treated as an afterthought. In Australia, the deductibility of premiums and the tax treatment of proceeds can depend on factors such as the purpose of the policy, who owns it, who receives the proceeds and whether the cover is revenue or capital in nature.
As a general principle, cover taken out to protect business revenue may be treated differently from cover taken out to protect capital, fund a buyout or repay a loan. Different types of cover, such as life, total and permanent disablement, trauma or income-style benefits, may also be treated differently.
Business owners should not assume that premiums will be deductible or that proceeds will be tax-free. If tax treatment is important to the structure, review it with a qualified tax adviser and read more about the tax treatment of business life insurance in Australia.
Questions to ask before choosing an ownership structure
A practical way to approach ownership is to start with the business purpose and work backwards. Useful questions include:
- What risk is being insured? Is the cover for lost revenue, succession, debt, personal family protection or a mix of purposes?
- Who needs the money if a claim is paid? The recipient should match the intended use of the funds.
- Who should control the policy? Consider who can cancel, change or maintain the cover.
- Who will pay the premiums? Premium funding should align with the intended accounting and tax treatment.
- Which legal documents need to match? Check shareholder agreements, partnership agreements, trust deeds, loan documents and buy-sell agreements.
- Could ownership change in the future? Consider new partners, departing shareholders, refinancing, business sales and restructures.
- What happens if premiums are missed? The business should have a process to monitor payment and policy status.
- What advice is needed? Complex structures often require input from an insurance adviser, accountant and commercial lawyer.
Common ownership mistakes to avoid
Business life insurance can be undermined by structural issues even when the insured amount appears appropriate. Common mistakes include:
- buying cover before deciding whether the purpose is key person, buy-sell, debt protection or personal protection;
- assuming the policy owner and beneficiary are interchangeable;
- using a buy-sell agreement that does not match the insurance ownership structure;
- failing to update policies after ownership changes, refinancing or business restructuring;
- not considering how proceeds may be taxed;
- allowing one owner to control cover that is meant to protect another party without safeguards;
- ignoring trust deed or company constitution restrictions; and
- not documenting the reason for the policy.
Ownership versus cover amount
Ownership and beneficiary structure answer the question of where the money should go and who controls the policy. A separate question is how much cover may be appropriate.
The insured amount may be influenced by the purpose of the cover. Key person cover might focus on revenue impact, replacement costs and working capital. Buy-sell cover may be linked to the value of an owner's interest. Debt protection may be linked to outstanding loans, guarantees and related costs.
For a broader framework, see this guide on how to estimate business life insurance cover needs. For buy-sell funding assumptions, a tool such as the Buy Sell Insurance Calculator may help with early scenario modelling, although it cannot replace tailored advice.
When to get professional advice
Professional advice is especially important where there are multiple owners, complex debt arrangements, trusts, family companies, personal guarantees, blended business and personal needs, or significant tax consequences.
Depending on the structure, you may need help from:
- a licensed insurance adviser or broker to compare policy options and insurer requirements;
- an accountant or tax adviser to review premium and proceeds treatment;
- a commercial lawyer to draft or review buy-sell, shareholder, partnership and loan documents; and
- an estate planning lawyer where personal ownership, beneficiaries or estates are involved.
You can also learn more about the role of brokers and professional assistance when working through policy structure and insurer requirements.
The aim is not simply to have a policy in place. The aim is to ensure the policy proceeds are controlled by the right party, paid to the right recipient and able to be used for the intended business outcome.
Key takeaways
The owner of a business life insurance policy should usually be chosen based on the purpose of the cover. A business-owned policy may suit key person or debt protection needs. Cross-owned, self-owned, entity-owned or trust-owned arrangements may be considered for buy-sell planning, depending on the agreement and ownership structure.
Before applying for cover, clarify who owns the policy, who pays the premiums, who receives the proceeds and how the arrangement interacts with legal and tax documents. Getting the structure right at the start can reduce confusion and support a smoother claim outcome if the policy is ever needed.
Published: Tuesday, 6th Oct 2026
Author: Paige Estritori


I hadn’t realised a buy-sell agreement could fall over just because the policy ownership doesn’t match the purchase obligation.