The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Applying for business life insurance in Australia usually involves more than requesting a quote. Insurers may ask about the business, the insured person, the purpose of cover, financial evidence and health information before offering terms.
Applying for business life insurance can feel unfamiliar if your business has not arranged cover before. A quote request is often only the first step. Before an insurer decides whether to offer cover, and on what terms, it may need to understand the business risk, the role of the person being insured, the amount of cover requested and the health and lifestyle profile of the insured person.
This guide explains the typical business life insurance application process in Australia, what information may be requested, how underwriting works and why requirements can differ for key person, buy-sell and debt protection purposes. It is general information only and does not replace advice from a licensed insurance adviser, accountant, solicitor or tax professional.
What happens before a business life insurance application?
The process often starts with a discussion about why the cover is being considered. For example, a business may want to protect against the loss of a founder, fund a buy-sell agreement, support loan repayment, or provide continuity while a replacement executive is recruited.
At the enquiry stage, you may only need to provide high-level information so quotes or indicative options can be explored. You can start with a business life insurance quote enquiry, but any initial estimate is generally not a final offer. Premiums, policy terms and availability usually depend on underwriting and the insurer's criteria.
A guided application can be useful because business cover involves both personal and commercial details. If you want support preparing information and understanding the questions asked, the broker referral page can help you connect with assistance. A broker or adviser may help explain policy structures and insurer requirements, but they will still need accurate information from you and the proposed insured person.
Information usually needed for a business life insurance application
The exact information requested varies between insurers, policy types, sums insured and the reason for cover. However, Australian business life insurance applications commonly involve several categories of information.
Business details
Insurers may ask for information that identifies the business and explains how it operates. This may include:
- the business name, ABN or ACN;
- business structure, such as company, partnership, trust or sole trader;
- industry, trading history and main activities;
- number of owners, directors, employees or key staff;
- ownership percentages and control arrangements;
- revenue, profit, debts or other financial indicators where relevant;
- details of related entities if the business structure is complex.
This information helps the insurer understand the commercial context and whether the proposed cover amount appears connected to a real business risk.
Purpose of the cover
The insurer will usually want to know why the cover is being arranged. Common business purposes include:
- Key person insurance: to help the business manage the financial impact of losing a person whose skills, relationships, knowledge or leadership are important to operations.
- Buy-sell or ownership protection: to help fund the transfer of an owner's interest if a specified event occurs, usually alongside a legal agreement.
- Business debt protection: to help repay or reduce business debts, personal guarantees or loan obligations if an insured person dies or suffers another insured event, depending on the policy.
- Revenue or continuity support: to provide funds that may help cover recruitment, temporary management, lost revenue or transition costs.
The purpose matters because it affects the type of evidence the insurer may ask for and whether the requested sum insured is considered reasonable.
Details of the person being insured
Business life insurance underwriting usually focuses heavily on the proposed insured person. The application may ask for:
- age, gender and residency details;
- occupation, duties and seniority;
- income or remuneration;
- work hours, travel and workplace hazards;
- qualifications, specialist skills or client relationships;
- smoking status, alcohol use and lifestyle factors;
- high-risk hobbies, sports or travel.
For key person insurance underwriting, the insurer may pay particular attention to what the individual contributes to the business and how their absence could affect revenue, operations, debt servicing or business value.
Medical and health information
Life insurance applications generally include personal health questions for the insured person. Depending on the insurer, age, cover amount and answers provided, this may include questions about:
- medical history and current health conditions;
- medications and treatment history;
- family medical history;
- height, weight and general health indicators;
- previous injuries, surgeries or hospital admissions;
- mental health history where relevant to the insurer's questions;
- past insurance applications, exclusions or loadings.
For larger sums insured or certain health disclosures, the insurer may request medical reports, blood tests, examinations or additional questionnaires. The requested information should be handled in line with privacy and consent requirements, and the insured person should understand what is being authorised before signing any consent forms.
Financial evidence
Financial underwriting helps an insurer assess whether the requested cover amount is justified for the stated business purpose. Depending on the case, this may involve:
- recent financial statements or management accounts;
- business tax returns or accountant-prepared documents;
- loan agreements or debt statements;
- business valuations or valuation formulas;
- shareholder, partnership or unit holder details;
- buy-sell agreement values or ownership percentages;
- evidence of the insured person's income, dividends or drawings.
Insurers generally do not ask for this information to make the process difficult. They use it to test whether there is a genuine financial exposure and whether the amount of cover aligns with that exposure.
Existing cover and insurance history
You may also be asked about existing insurance held by the business or the insured person. This can include personal life insurance, income protection, trauma cover, total and permanent disability cover, group cover through superannuation, or other business-owned policies.
Existing cover can affect the insurer's view of the total amount insured across all policies. It may also help identify whether a new application is replacing, supplementing or duplicating existing protection.
Understanding insurable interest in business insurance
In a business life insurance application, the insurer usually needs to be satisfied that there is an insurable interest. In simple terms, this means the business, owners or other policy beneficiaries would suffer a genuine financial impact if the insured event occurred.
Examples may include a company relying on a founder's expertise, partners needing funds to buy out a deceased owner's interest, or a lender requiring debt protection for a key guarantor. The insurer may ask for evidence that connects the insured person to the financial risk being insured.
Insurable interest is one reason the application process for business cover can be more detailed than a simple personal life insurance quote. It is also why the same person might be underwritten differently depending on whether the cover is for key person protection, buy-sell funding or debt protection.
How business life insurance underwriting works
Business life insurance underwriting is the process an insurer uses to decide whether it will offer cover, how much cover it may offer, and what premium or policy terms may apply. Underwriting can include both medical underwriting and financial underwriting.
| Underwriting area | What it looks at | Why it matters |
|---|
| Medical underwriting | The insured person's health, medical history, lifestyle and occupational risks. | Helps the insurer assess the likelihood of a claim under the type of cover requested. |
| Financial underwriting | Business revenue, profit, valuation, debts, ownership and the purpose of cover. | Helps confirm the amount of cover is commercially reasonable and connected to a financial loss. |
| Policy structure review | Who owns the policy, who is insured, who may receive proceeds and how the cover is intended to be used. | Helps align the application with the business purpose and may identify legal, tax or ownership issues to discuss with professionals. |
Underwriting may result in several possible outcomes. An insurer may offer cover on standard terms, offer cover with a premium loading, apply exclusions, request a lower sum insured, postpone a decision, or decline the application. These outcomes depend on individual circumstances and the insurer's assessment criteria.
Why underwriting can affect premiums
Premiums are influenced by many factors, including the insured person's age, health, smoking status, occupation, cover amount, policy type and the insurer's pricing approach. Business-specific factors can also matter, particularly when the requested sum insured is linked to revenue, profits, debt or ownership value.
For a broader explanation of pricing factors, you can read more about the costs of business life insurance for Australian SMEs. Keep in mind that any examples or general cost explanations are not a guarantee of the premium an insurer may offer after underwriting.
How requirements differ by type of business cover
Although the same broad application process may apply, different business purposes can require different supporting evidence.
Key person cover
For key person cover, the insurer may focus on the person's contribution to the business. This could include revenue generation, technical expertise, management responsibility, client relationships or their role in securing finance. Evidence may include financial statements, role descriptions, remuneration details and an explanation of the expected financial impact if that person could no longer work in the business.
Buy-sell cover
For buy-sell insurance, the insurer may ask about ownership interests, valuation methods and the agreement that governs transfer of ownership. A solicitor-prepared buy-sell agreement or shareholder agreement may be relevant. The application may need to show how the insured amount relates to the value of the owner's share.
Debt protection cover
For debt protection, the insurer may ask for loan amounts, repayment obligations, personal guarantees and the connection between the insured person and the debt. This helps demonstrate why the policy amount has been requested and who would be affected if the insured person died or became seriously ill, depending on the cover selected.
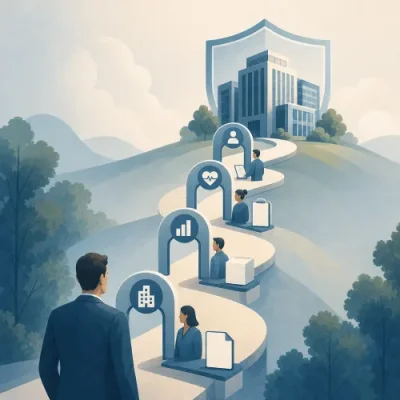
Common stages in the life insurance quote process
While each insurer and adviser may use a different workflow, the life insurance quote process for a business often follows these broad stages:
- Initial enquiry: the business provides basic details about the cover being considered and the people involved.
- Needs discussion: the purpose, ownership structure, cover amount and potential policy type are explored.
- Indicative quote or options: preliminary pricing may be discussed, subject to underwriting and insurer acceptance.
- Application preparation: the business and insured person provide personal, medical, financial and commercial information.
- Underwriting assessment: the insurer reviews the application and may request further evidence.
- Offer of terms: the insurer may offer cover, vary terms, request changes or decline the application.
- Acceptance and policy issue: if the applicant accepts the terms and pays the required premium, the policy may be issued according to the insurer's process.
- Ongoing review: cover may need to be reviewed as the business changes, debts reduce, ownership changes or key people join or leave.
Preparing before you apply
Preparation can make the application process smoother, although it cannot guarantee acceptance or pricing. Before applying, business owners and directors may wish to gather:
- current ownership and entity details;
- recent business financials or accountant-prepared summaries;
- loan balances and guarantee details if debt protection is relevant;
- business valuation documents or valuation methodology if buy-sell cover is relevant;
- role descriptions for key people being insured;
- details of existing insurance policies;
- contact details for accountants, solicitors or advisers who may need to provide supporting information.
The insured person should also be ready to answer health and lifestyle questions carefully. In Australia, applicants are generally expected to take reasonable care not to make a misrepresentation when answering insurer questions. If unsure, it may be better to disclose information and let the insurer decide whether it is relevant.
Questions to ask before submitting an application
Business life insurance can interact with business succession, tax, ownership and estate planning. Before submitting an application, consider asking:
- What is the main purpose of the cover?
- Who should own the policy?
- Who would receive any policy proceeds?
- How was the cover amount calculated?
- Does the policy structure match the business agreement or loan arrangement?
- Could premiums or proceeds have tax implications?
- What information is needed from the accountant, solicitor or lender?
- What happens if the insurer offers modified terms?
- How often should the policy be reviewed?
These questions are especially important where more than one owner, entity or beneficiary is involved. Legal and tax consequences can vary depending on the structure, so professional advice may be appropriate before finalising policy ownership or beneficiary arrangements.
What to expect after the policy is issued
The application process does not end the need for ongoing attention. A business may change quickly. Revenue may grow, debts may reduce, ownership may shift and key people may leave or join. If the policy is not reviewed, the cover may no longer match the business risk it was originally designed to address.
It can be useful to review business life insurance when there is a major loan refinance, new shareholder, sale of equity, updated buy-sell agreement, substantial revenue change, or change in the health or role of an insured person. Any changes to cover will depend on the insurer's terms and may require further underwriting.
Key takeaway
A business life insurance application is designed to show the insurer who is being insured, why the cover is needed, whether there is a genuine business risk, and whether the requested amount is commercially reasonable. The process may involve business information, financial evidence, medical details and questions about policy ownership.
Being prepared can reduce confusion and help the application progress, but it does not guarantee cover, premium levels or acceptance. Outcomes depend on the insured person's circumstances, the business purpose, the evidence provided and the insurer's underwriting criteria.
Published: Tuesday, 6th Oct 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.